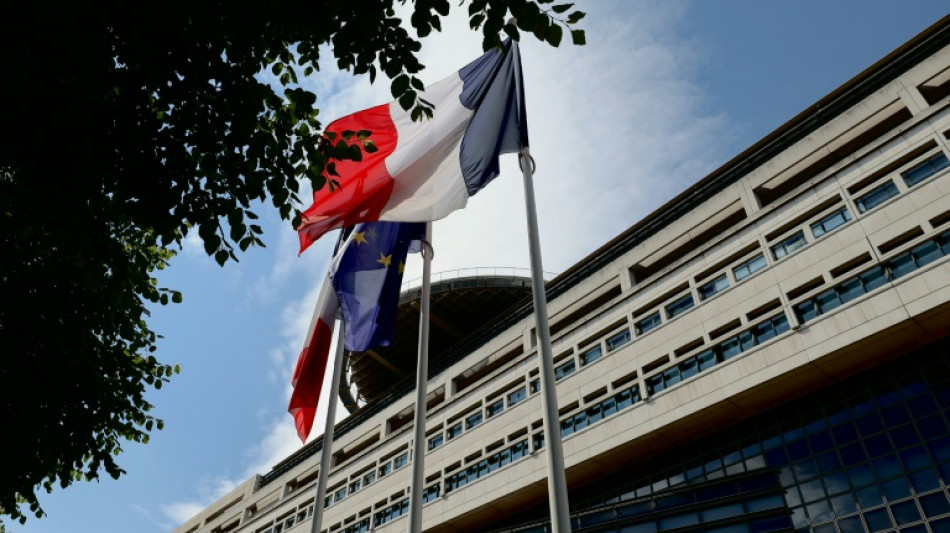
Five things to know as French bond yield tops 5% / Photo: Thomas SAMSON - AFP/File
 London
 10 °C
 Manchester
10 °C
 Glasgow
 10 °C
 Dublin
11 °C
 Belfast
8 °C
 Washington
 12 °C
 Denver
11 °C
 Atlanta
13 °C
 Dallas
14 °C
 Houston Texas
21 °C
 New Orleans
17 °C
 El Paso
16 °C
 Phoenix
23 °C
 Los Angeles
 17 °C
San Diego
17 °C
San Francisco
16 °C
Chicago
12 °C
Minneapolis
9 °C
Seattle
 7 °C
Portland
9 °C
Salt Lake City
 13 °C
Las Vegas
19 °C
Miami
23 °C
Jacksonville
17 °C
San Antonio
14 °C
Bermuda
27 °C
Nassau
 11 °C
Iqaluit
-5 °C
Yellowknife
6 °C
Anchorage
 1 °C
Fairbanks
-5 °C
Barrow
-6 °C
Calgary
0 °C
Edmonton
6 °C
Winnipeg
5 °C
Goose Bay
4 °C
Halifax
12 °C
Boston
8 °C
Ottawa
6 °C
Toronto
7 °C
Detroit
8 °C
Cleveland
8 °C
New York
11 °C
Baltimore
12 °C
Philadelphia
11 °C
Nuuk (Godthåb)
-4 °C
Hong Kong
29 °C
Singapore
30 °C
Melbourne
 21 °C
Canberra
13 °C
Adelaide
17 °C
Darwin
29 °C
Perth
18 °C
Fort Worth
13 °C
Honolulu
24 °C
Sydney
19 °C
Johannesburg
28 °C
Dubai
35 °C
Mumbai
33 °C
Zürich
9 °C
Tokyo
26 °C
Seoul
7 °C
Delhi
27 °C
Beijing
8 °C
Riyadh
36 °C
Prague
16 °C
Pennsylvania
9 °C
Valletta
25 °C
Manama
33 °C
Warsaw
16 °C
Stockholm
11 °C
A sell-off in French government bonds amid a budget standoff and after violent protests pushed the yield on the benchmark 10-year note past five percent Wednesday, the highest level since 2002.
The spread between French and German bonds, considered the European benchmark of creditworthiness, has also surged to 1.6 percentage points.
Here is what you need to know about German government bonds, or Bunds, and France's 10-year OAT bonds.
How are yields determined?
A bond's yield measures the interest paid on government debt relative to its price, and reflects the annual return an investor would earn over the period the bond is held, assuming it is held to maturity.
Yields go up as prices go down and vice versa.
A bond bought for 100 euros that pays one euro in interest has a yield of one percent. If demand for the bond falls and its price slumps to 50 euros, the yield has risen to two percent.
Many factors affect the supply and demand of bonds and hence their yield and price.
A major influence is the borrower's risk profile. Germany has traditionally had solid public finances and is seen as a safer bet in terms of paying back its debts than France, hence the lower yield on German government bonds.
Inflation is another. Faster price growth means investors demand a higher rate of return to try to protect the real value of their holdings.
The European Central Bank between 2015 and 2021 supported the eurozone sovereign debt market by buying government bonds from third parties like banks.
It is now selling those off even as big US companies issue debt to fund the AI infrastructure boom, leading to lots of bonds for the market to absorb.
Is the Bund still the benchmark?
Freely traded and considered virtually risk-free, the Bund has a haven status that is "not being called into question", Frederik Ducrozet of the Swiss bank Pictet told AFP.
Nevertheless, "the situation is very different from the sovereign debt crisis of the early 2010s", he added, when investors selling Italian or Spanish debt almost automatically bought Bunds.
Investors now have more options, Ducrozet said.
As well as the growth in corporate bonds, other countries' debt is looking more attractive -- for instance, yields are rising in Japan as inflation has returned following decades of deflation.
German borrowing costs are also rising
Germany is borrowing and spending more to try to revive its ailing economy after years of slow growth.
It also wants to pay for rearmament as Russia and Ukraine fight a war on Europe's eastern flank.
Berlin is "now adopting the approach of responding to crises, whether the pandemic or spikes in energy prices, with a massive increase in public spending", said Joerg Kraemer, chief economist at Commerzbank.
Why is the gap with France growing?
The spread between the 10-year yield on French OATs and German Bunds amounts to the extra payment investors demand to hold French instead of German bonds.
German government debt is just 66 percent of the country's gross domestic product, compared to almost 120 percent for France.
Civil unrest and a presidential election next year also make it hard for Paris to cut spending or raise taxes, measures that could bolster investor confidence in French government debt.
How high could the spread go?
The Franco-German spread is relatively wide, but the eurozone saw far larger gaps in borrowing costs during the eurozone debt crisis of the early 2010s.
A limiting factor is the European Central Bank's so-called Transmission Protection Instrument (TPI), which was created in 2022 and allows the central bank to intervene in eurozone bond markets if a member state's debt is sold off in a disorderly manner.
But the TPI, which has never been used, can be activated only in cases where a bond sell-off is considered unjustified. Analysts note this is not the case with indebted France.
ECB President Christine Lagarde has reacted coolly when asked about the prospect of the central bank intervening to support French debt.
"There are particular circumstances that lead to some countries being more affected, France being a case in point," she said of rising yields at a CNN event in Bangkok this month.
"And for that one, the primary and first solution lies at home in France. And it has to do with fiscal policies."
jpl-vbw/sr/js
R.Accetta--INP